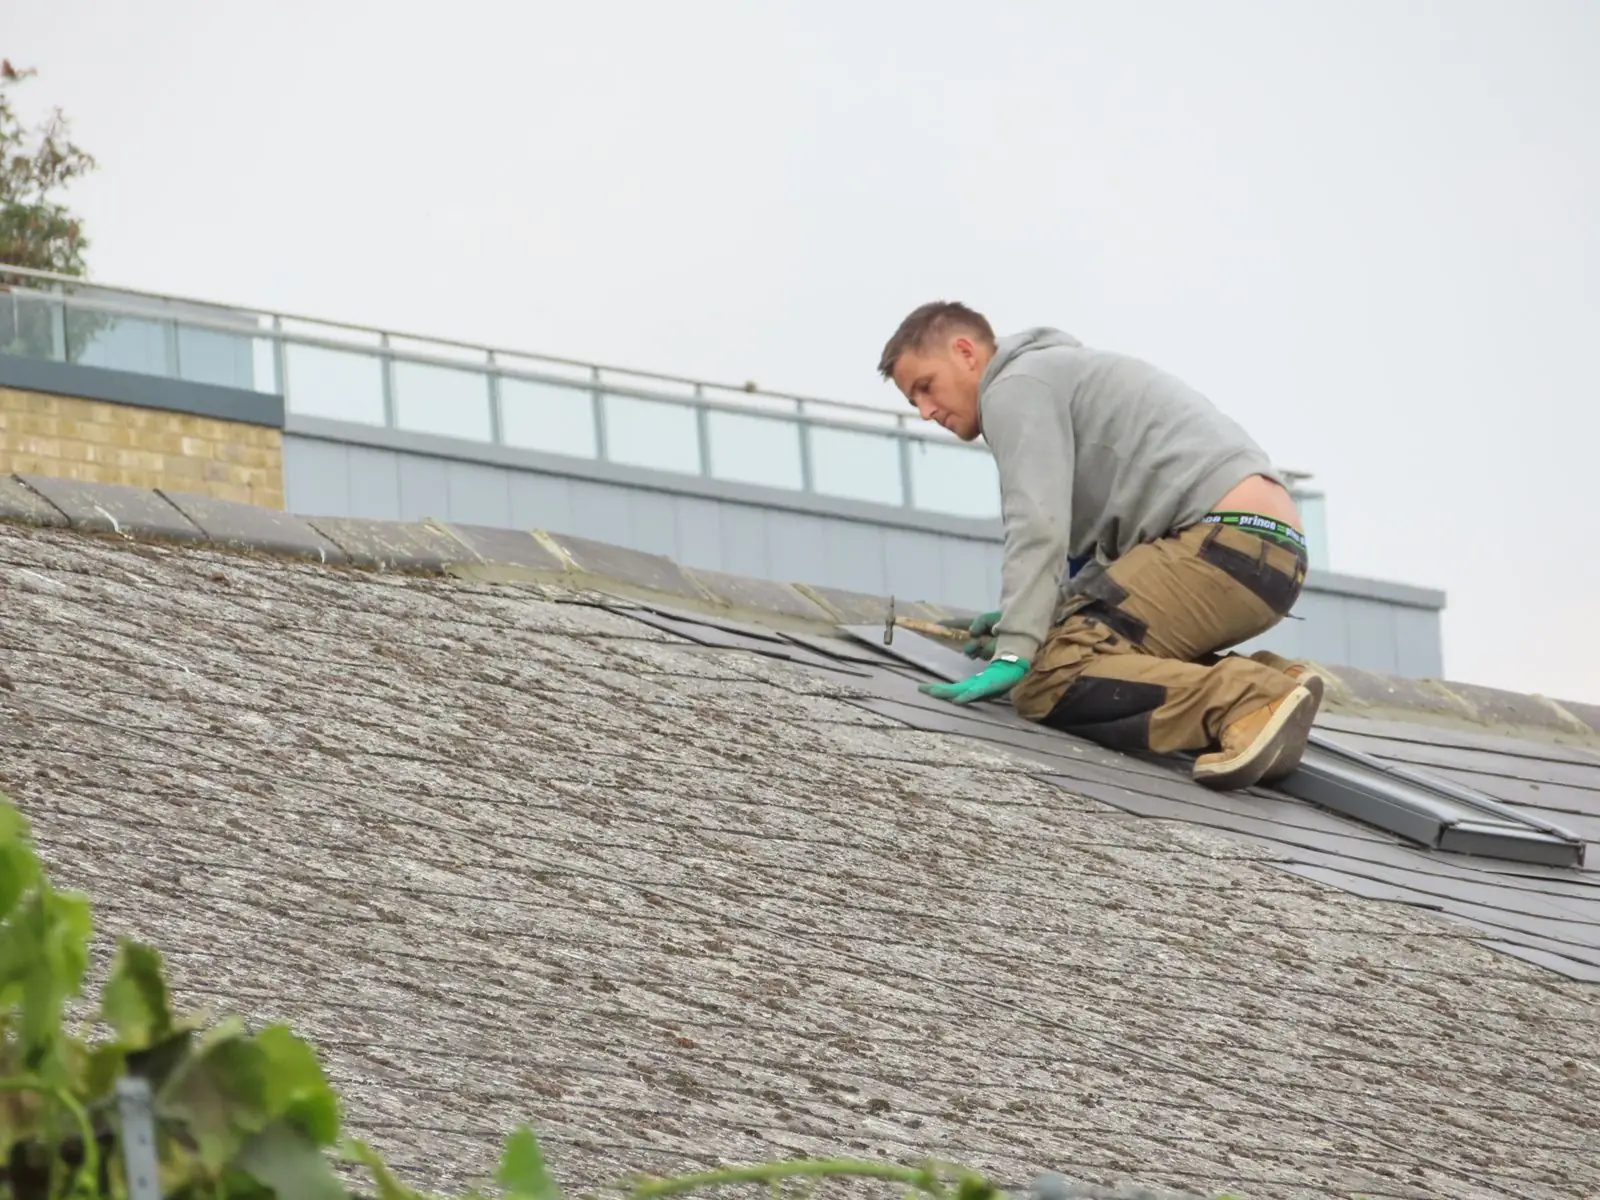
Repair or replace: the core roof dispute
The most common roof disagreement is not whether a storm hit the house. It is whether the damage calls for a few squares of repair or a full slope or full roof replacement. Carriers often price spot repairs; contractors often say the roof cannot be repaired without creating a patchwork or violating code. Appraisal is well suited to this kind of scope argument because it turns on measurements, material availability and repairability.
The 2022 reforms and roof terms in your policy
Florida’s 2022 property insurance legislation changed how roof claims are handled in several ways. Insurers gained more room to offer policies with roof payment schedules or actual cash value terms for older roofs, which can mean depreciation is deducted from roof payments even when the rest of the dwelling is on a replacement cost basis. Rules around when a partially damaged roof must be fully replaced to meet code were also revised, including treatment of roofs already built to newer code standards.
We will not guess at your policy’s roof terms. We read the actual endorsements, identify any roof schedule or ACV language and price the claim accordingly. Our article on Florida roof claims after the 2022 reforms covers the background, and it is general information rather than legal advice.
Measurement is where money hides
A roof estimate lives or dies by its quantities. Small errors in pitch, waste factor, ridge length or starter course add up quickly. We verify:
- Total squares by slope, with pitch confirmed
- Waste factor appropriate to the roof geometry, hips and valleys
- Linear feet of ridge, hip, valley, drip edge and eave
- Underlayment type required by current code
- Steep and high-roof charges where the pitch or height warrants them
Try our roof measurement calculator to get a rough sense of squares before we inspect.
Matching tile and discontinued shingles
Concrete and clay tile roofs are common across Florida, and replacement tile that matches in profile and color is frequently unavailable. The same is true of shingle lines that have been discontinued. Florida law generally addresses matching for residential claims, requiring reasonable uniformity in appearance, though how that applies to your roof depends on the facts and your policy. We document availability with supplier information so the matching argument rests on evidence.
Depreciation and roof age
Roof age is now a central factor in Florida claims. Depreciation should reflect the roof’s actual condition and expected life, not just a calendar calculation. A well-maintained tile roof and a neglected shingle roof of the same age are not equivalent. If your policy pays roofs at actual cash value, check the carrier’s depreciation figure with our ACV depreciation calculator.
Working with Florida Insurance Appraiser on a roof claim
Florida Insurance Appraiser inspects the roof directly when it is safe to do so, photographs each slope, records test squares where appropriate and prepares an itemized estimate. We then negotiate with the carrier’s appraiser and, if needed, present the remaining items to an umpire. We do not decide coverage, and we cannot promise any result, but we make sure the roof is measured and priced correctly.
What to gather before you call
- Policy endorsements, especially any roof payment schedule or ACV roof language
- Roof permit or installation date, if you know it
- Roofer’s estimate and any repairability opinion
- Photos of each slope and interior leaks
- Carrier’s roof report, diagram or aerial measurements
- Prior roof repair invoices or inspection reports
Frequently asked questions
Can appraisal decide whether my roof gets fully replaced?
Appraisal can decide the scope and cost of repairing covered damage, which often includes whether repair is feasible or replacement is required to restore the roof. It cannot override a coverage denial.
My policy pays my roof at actual cash value. Is appraisal still useful?
It can be. Depreciation is part of the amount of loss, and appraisers can dispute both the replacement cost and how much depreciation was applied.
What changed with Florida roof claims in 2022?
The reforms changed several roof-related rules, including allowing roof payment schedules on some policies and revising when partial damage triggers full replacement under code. Check your policy and consult an attorney for specifics.
Do you need to get on the roof?
When it is safe, yes. Hands-on inspection gives better measurements and evidence than photos alone. We use other documentation where access is unsafe.