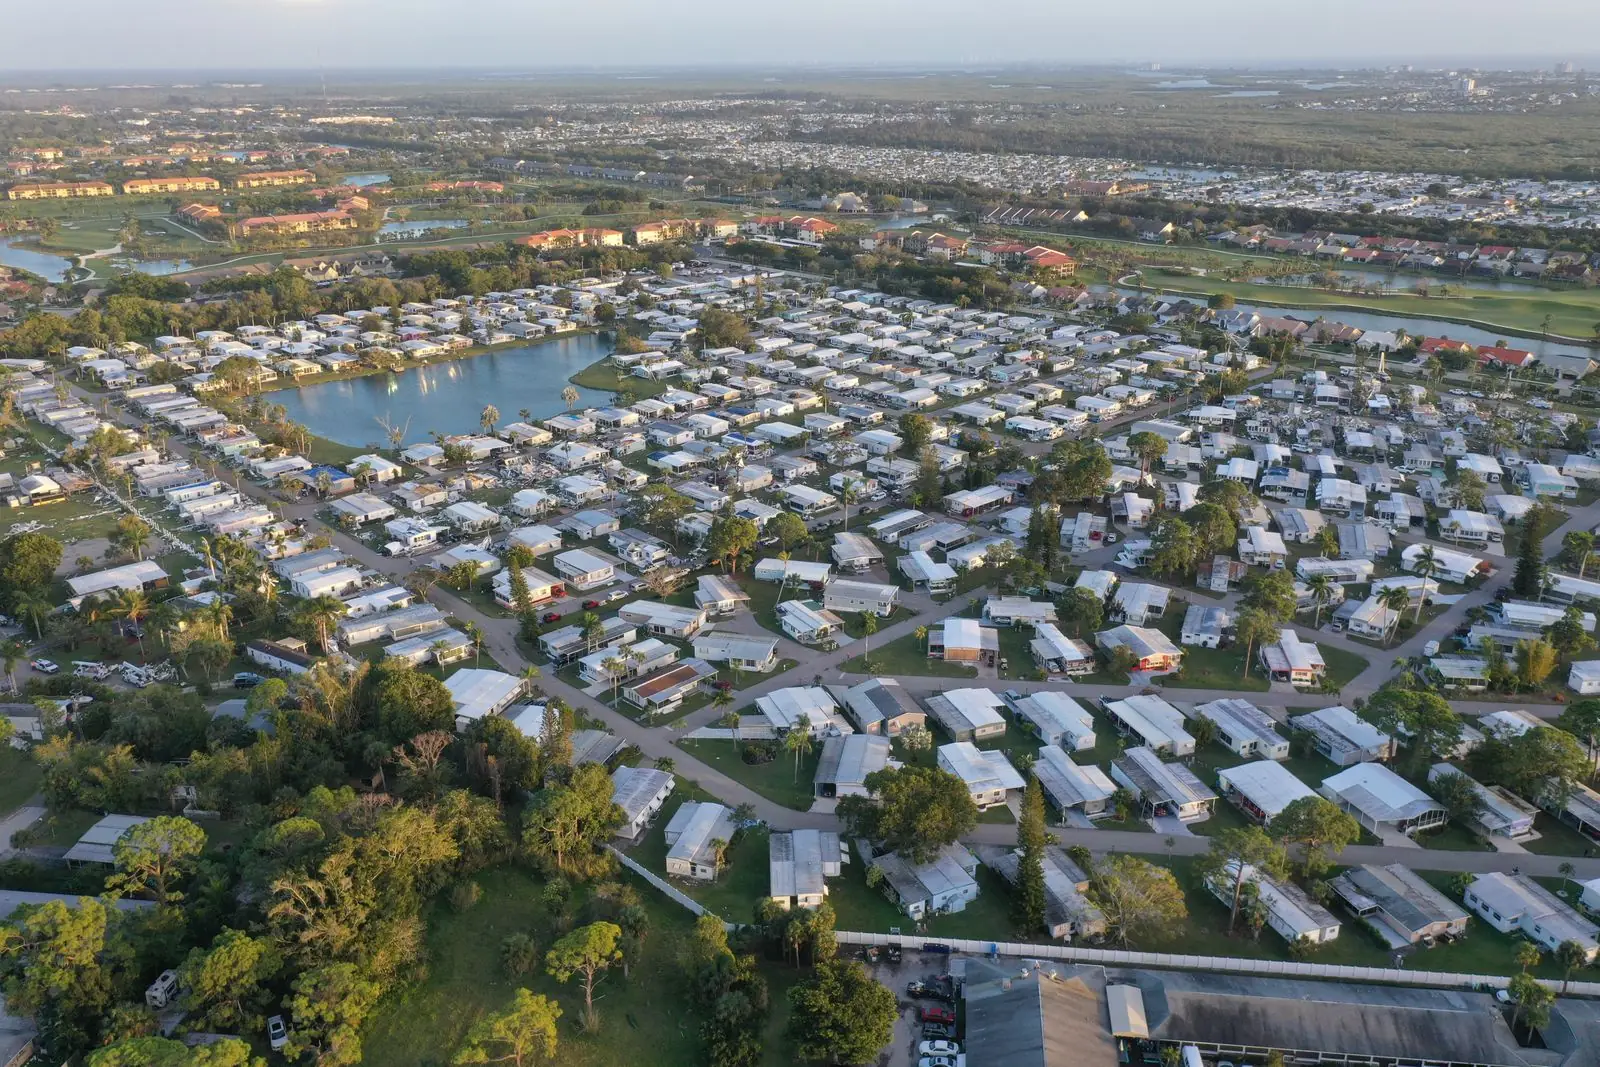
After Ian: the wind-versus-water question
Hurricane Ian changed the claim landscape in Southwest Florida. On Fort Myers Beach, Sanibel, Pine Island, Matlacha and along the Caloosahatchee, many homes were hit by both extreme wind and storm surge. Homeowners policies generally cover wind and exclude flood, while flood policies, often through the NFIP, cover surge with their own limits. The result is a long list of claims where the insurer attributes most of the damage to water and the owner believes wind did much of it first.
Deciding cause is often a coverage matter outside appraisal, and courts and policies differ on how far appraisers may go. But once the scope is defined, the cost of wind-damaged roofs, windows, soffits and interiors still has to be measured accurately. Our hurricane claim appraisal work is built around documenting those layers.
Cape Coral and the canal-front block home
Cape Coral was built out over decades as a grid of canals lined with single-story concrete block homes, many with tile or shingle roofs, pool cages and docks. Ian’s wind tore pool enclosures and roofs across the city, and water got into homes through damaged openings. Many of these houses are similar in layout, which can tempt insurers toward template estimates that miss what is actually in a particular home.
We inspect each property on its own terms. The roof measurement calculator can help you check whether your carrier’s roof area is in the right range before we even arrive.
Repair, rebuild and the 50 percent conversation
In flood zones, local floodplain rules generally require a heavily damaged structure to be brought into compliance, often by elevating it, when repair costs reach a set share of the building’s value. That “substantial damage” determination is made by the local building official, not by an appraiser, and it can change what a realistic repair looks like. We take any such determination into account when building a scope, and we price what a contractor would actually need to do.
Lee County’s post-Ian construction market also pushed labor and material costs well above normal, which is one reason older estimates often fall short. Our Xactimate estimate review compares a carrier’s pricing line by line against current conditions.
How Florida Insurance Appraiser works in Lee County
Florida Insurance Appraiser serves Fort Myers, Cape Coral, the islands and the rest of Lee County as part of our statewide practice. We are appraisers, not public adjusters or attorneys: our work is to value covered damage and defend that valuation in the appraisal process, with an umpire resolving any items the two appraisers cannot settle. Florida deadlines for reporting and reopening claims have tightened in recent years, so check yours promptly.
Storms that shaped Fort Myers claims
- 2004Hurricane Charley
Charley came ashore at Cayo Costa and Punta Gorda just north of Lee County, damaging Captiva, Pine Island and northern Lee communities. - 2017Hurricane Irma
Irma made its Florida mainland landfall at Marco Island and brought widespread wind and tree damage to Lee County. - 2022Hurricane Ian
Ian made landfall near Cayo Costa as a strong Category 4, and its storm surge devastated Fort Myers Beach, Sanibel, Pine Island and riverfront Fort Myers.
Claim issues we see in Lee County
- Wind vs. storm surge allocation after Ian
- Cape Coral canal-front block homes
- Rebuild costs vs. repair estimates on heavily damaged homes
- Roofs damaged by wind then exposed to months of rain
- Supplemental damage found during repairs
Areas we cover around Fort Myers
- Downtown Fort Myers
- McGregor Boulevard corridor
- Cape Coral
- Fort Myers Beach
- Sanibel
- Lehigh Acres
- Estero
- North Fort Myers
Frequently asked questions
Can appraisal decide how much of my Ian loss was wind vs. surge?
Practice varies, and many causation questions are treated as coverage issues outside appraisal. Appraisal reliably sets the cost of the damage once the covered scope is identified. If causation is the main fight, consider talking to an attorney.
Is it too late to use appraisal on an older Lee County claim?
Possibly not, but Florida law and your policy set deadlines for supplemental and reopened claims. Check your policy, and use our claim deadline calculator as a general guide, then confirm with an attorney if you are close.
Do you work on Sanibel, Captiva and Fort Myers Beach?
Yes. We serve the barrier islands and all of Lee County, including Bonita Springs, Estero and Lehigh Acres.