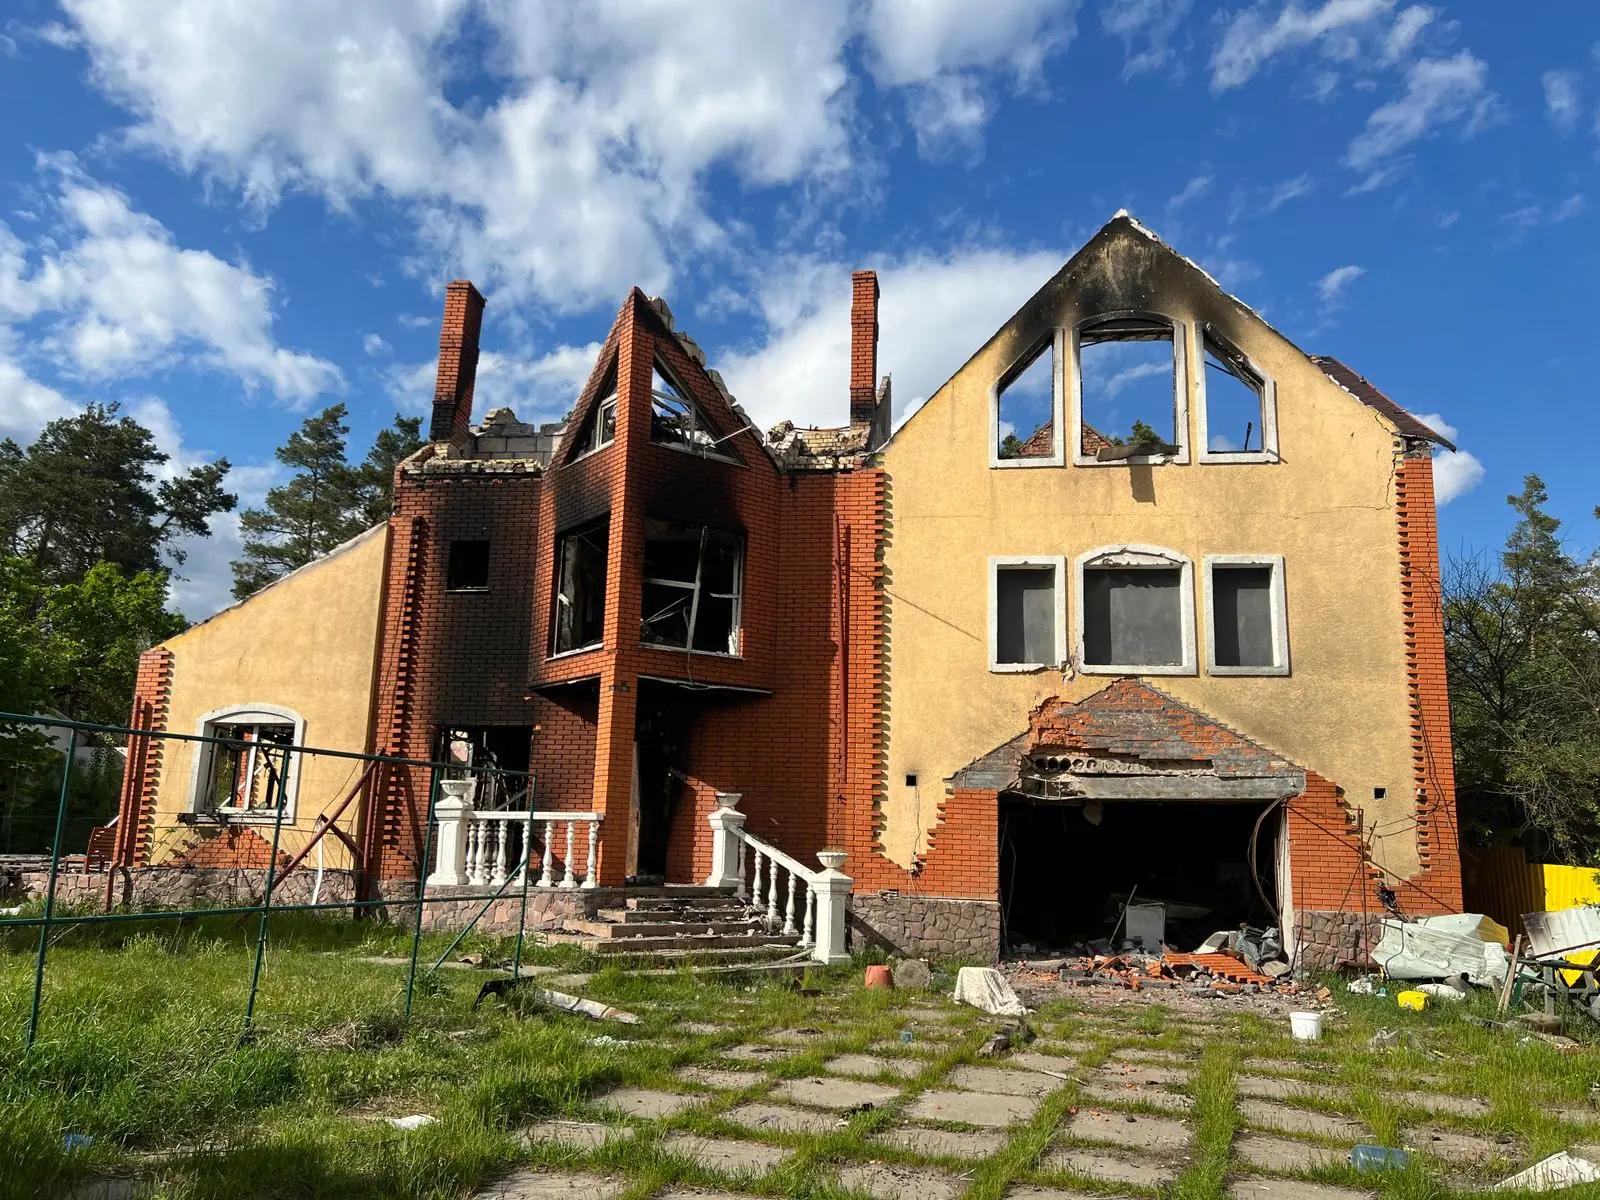
Clean, seal or replace?
The biggest dollar swing in many fire claims is the decision between cleaning and replacing. Carriers lean toward cleaning and sealing drywall, framing and contents; homeowners often find that odor persists after cleaning. Appraisal is a reasonable forum for this argument when the evidence supports it: soot testing results, photos of residue in unaffected-looking rooms and documentation of odor that survived an initial cleaning attempt.
Structural rebuild scope
After a significant fire, the structure may need partial or full reconstruction. That brings in items carrier estimates sometimes leave thin:
- Demolition and debris removal, including disposal fees
- Engineering for fire-weakened framing or trusses
- Electrical rewiring, which often must meet current code
- Full HVAC cleaning or replacement of ductwork
- Permits and inspections
- General contractor overhead and profit for multi-trade work
Ordinance or law and code upgrades
When a substantially damaged Florida home is rebuilt, local building departments generally require the new work to meet current code. That can mean upgraded windows and doors in wind-borne debris regions, roof-to-wall connections, electrical panels and more. Many policies include ordinance or law coverage, often as a percentage of Coverage A, to pay for these upgrades. We identify code-driven line items separately so they are valued against the right coverage.
Contents after a fire
Contents claims after a fire can include hundreds or thousands of items, many of them smoke-damaged rather than burned. A complete, room-by-room inventory with replacement costs and approximate ages is the foundation of any contents appraisal. Start with our contents inventory builder, and check the carrier’s depreciation with the ACV depreciation calculator.
Additional living expense for a long rebuild
Fire rebuilds in Florida can take many months, especially when permits and contractor availability are tight. Additional living expense coverage may pay for reasonable rent, mileage and other increased costs while you are out of the home, subject to policy limits and time limits. Florida Insurance Appraiser can help document ALE as part of the overall amount of loss.
Commercial fire losses
For businesses, a fire claim also raises business income and extra expense questions, plus tenant improvements and equipment. See our commercial claim appraisal page for how we approach those. As always, appraisal decides the amount of loss and does not resolve coverage disputes such as cause-of-fire or vacancy issues. Florida Insurance Appraiser provides general information here, not legal advice.
Protecting the property after a fire
Most policies require you to take reasonable steps to prevent further damage after a loss. In Florida, an open roof or broken windows invite rain within days, which can turn a fire claim into a fire and water claim. Board-up, tarping and temporary fencing costs are usually part of the claim, so keep the invoices. Avoid discarding damaged materials before they are documented, because the carrier’s adjuster and the appraisers may need to see them to agree on scope.
What to gather before you call
- Fire department incident report number
- Carrier estimate, contents valuation and payment letters
- Photos of every room, including those with only smoke damage
- Soot or air quality testing results, if any
- Room-by-room contents inventory
- Rental, hotel and mileage receipts while displaced
Frequently asked questions
Can appraisal resolve a dispute about whether smoke-damaged items should be replaced?
Yes, if the carrier has accepted the loss. Whether an item can be restored by cleaning or must be replaced is a valuation question appraisers commonly address.
Does appraisal cover code upgrades after a fire?
Appraisers can value code-required work, but whether and how much is paid depends on your ordinance or law coverage and its limit.
What if the carrier is investigating the cause of the fire?
Cause and coverage investigations are outside appraisal. Appraisal applies to the amount of a covered loss.
Can contents be included in the appraisal?
Yes. Contents can be part of the amount of loss, and a detailed inventory makes that portion much stronger.