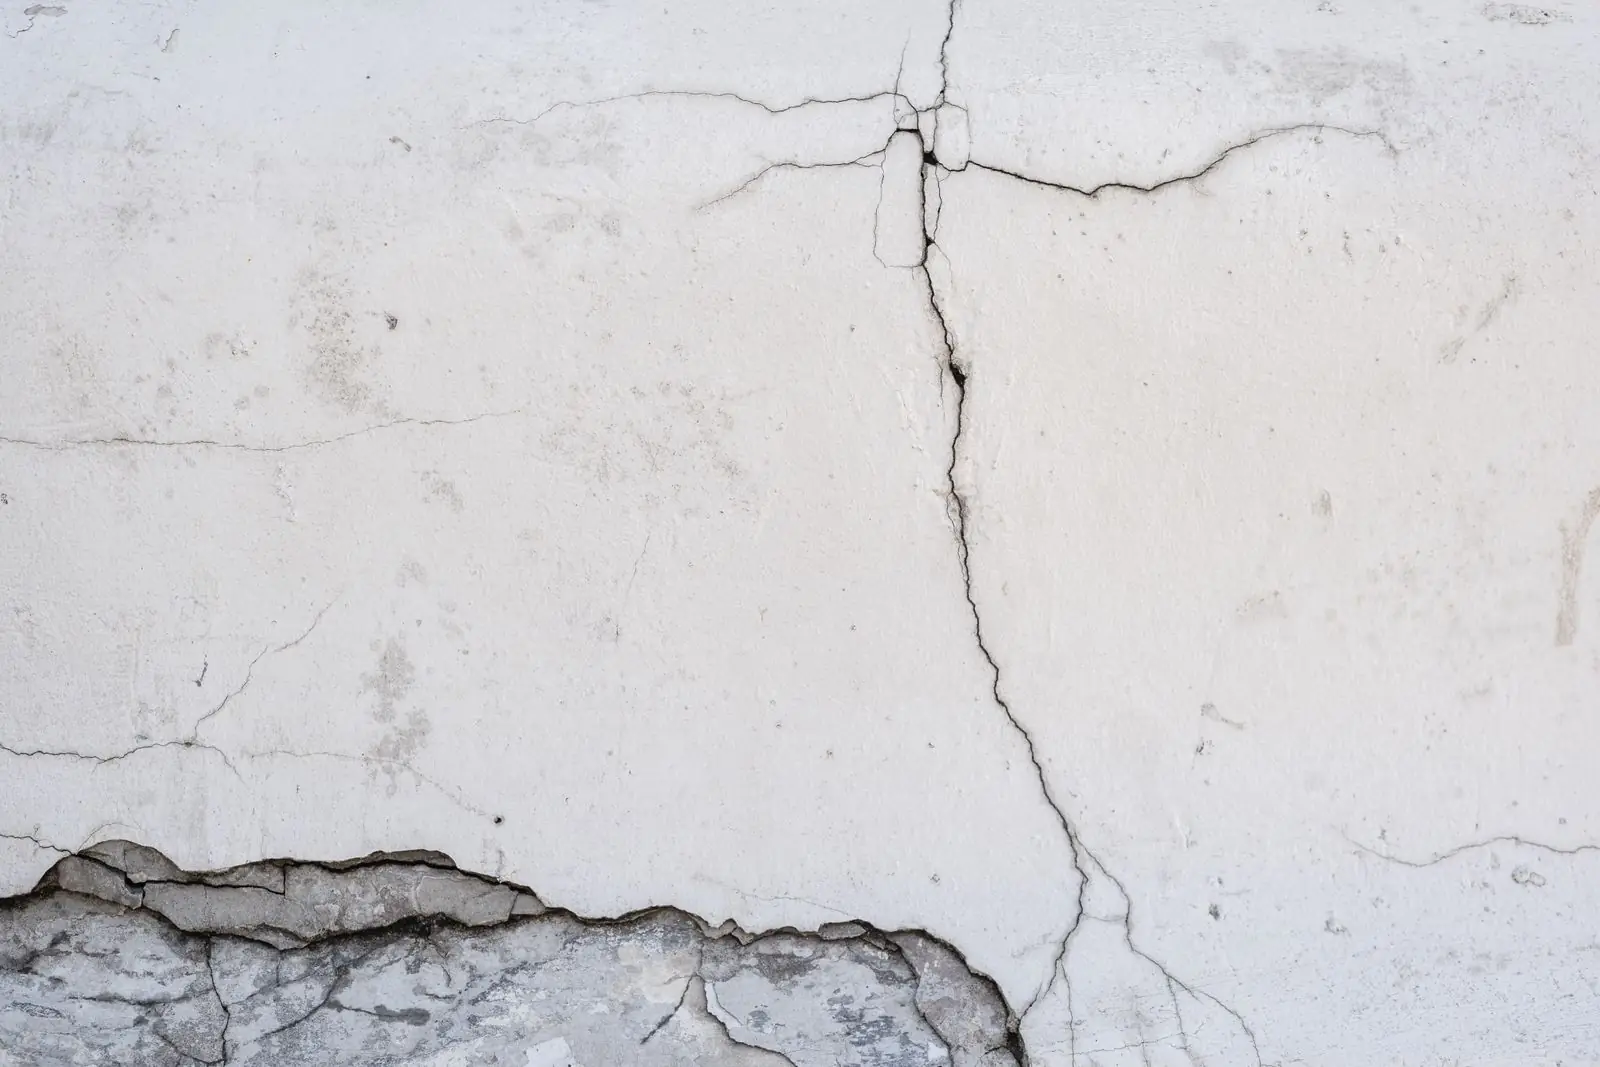
Sinkhole coverage versus catastrophic ground cover collapse
Florida treats these as two different things. Standard homeowners policies are generally required to include coverage for catastrophic ground cover collapse, which is a narrow definition: roughly, an abrupt collapse of the ground cover, a visible depression, structural damage to the building and condemnation of the structure. Broader sinkhole loss coverage, which can reach gradual settlement and cracking caused by sinkhole activity, is usually optional and purchased separately, often with its own deductible.
Which coverage you have, and whether it applies, is a coverage question. Read your declarations page and endorsements carefully, and talk to an attorney if the carrier has denied the claim.
Florida’s sinkhole-specific procedures
Florida has statutes specific to sinkhole claims that address testing, engineering reports and how repair payments are made. Policies commonly require that stabilization and foundation repairs follow the recommendations of a professional engineer, and payments may be tied to entering into a repair contract. Florida’s Department of Financial Services also offers a neutral evaluation program for certain sinkhole disputes, which can be an alternative or a complement to appraisal. We work within whatever framework your policy and current law set out.
What appraisal can value in a sinkhole claim
Once a sinkhole loss is accepted, disagreements tend to cluster around:
- The cost of the engineer-recommended subsurface work, such as grouting or underpinning
- Above-ground repairs: wall cracks, slab cracking, doors and windows out of square, tile and drywall
- How much interior finish work is needed after stabilization causes further movement
- Pool deck, driveway and other structures
- Temporary relocation costs during foundation work
We do not perform engineering or select stabilization methods. We price the scope that the engineering supports and challenge estimates that leave pieces out.
Why above-ground damage gets underestimated
Carriers sometimes approach cosmetic repairs as simple patch-and-paint work. In practice, stabilization can move a structure again, re-opening cracks and stressing finishes. A credible estimate sequences cosmetic repairs after subsurface work and accounts for the realistic extent of drywall, tile and trim replacement. We also document cracks with measurements and dated photos so changes over time are visible.
Where we see sinkhole claims
Hernando, Pasco and Hillsborough counties have historically seen many sinkhole claims, along with Marion, Citrus and Polk. Florida Insurance Appraiser assists homeowners throughout the region, including Tampa and Orlando area communities, as well as other parts of the state.
Getting started
Send us the engineering report, the carrier’s estimate and your contractor’s numbers. We will tell you plainly whether the dispute looks like an amount-of-loss issue that appraisal can address, or a coverage issue that needs a lawyer. Florida Insurance Appraiser does not provide legal advice, and nothing on this page should be read as such. For an overview of the full sequence, see the appraisal process.
Documenting movement over time
Sinkhole claims can stretch over long periods while testing, engineering and repair contracting play out. During that time, cracks may widen and new ones may appear. We recommend keeping a simple log: date, location, crack width measured with a crack gauge or ruler, and a photo with a reference object in frame. That record helps separate pre-existing settlement from sinkhole-related movement and gives both appraisers a shared factual baseline when they sit down to compare estimates.
What to gather before you call
- Declarations page showing sinkhole or catastrophic ground cover collapse coverage
- Engineering and geological testing reports
- Carrier’s estimate and any repair contract requirements
- Dated crack photos and measurements over time
- Foundation repair contractor proposals
- Prior inspection or repair records for the home
Frequently asked questions
Is sinkhole damage covered by a standard Florida homeowners policy?
Standard policies generally must cover catastrophic ground cover collapse, which is narrowly defined. Broader sinkhole loss coverage is typically optional. Check your declarations page.
Can appraisal decide whether a sinkhole caused my cracks?
No. Causation and coverage are not decided in appraisal. Appraisal values an accepted loss.
Do you recommend grouting or underpinning?
No. Stabilization methods are an engineering decision. We value the scope that the engineering report supports.
Is there a state program for sinkhole disputes?
Florida’s Department of Financial Services has offered a neutral evaluation program for certain sinkhole claims. Check with DFS for current eligibility and procedures.