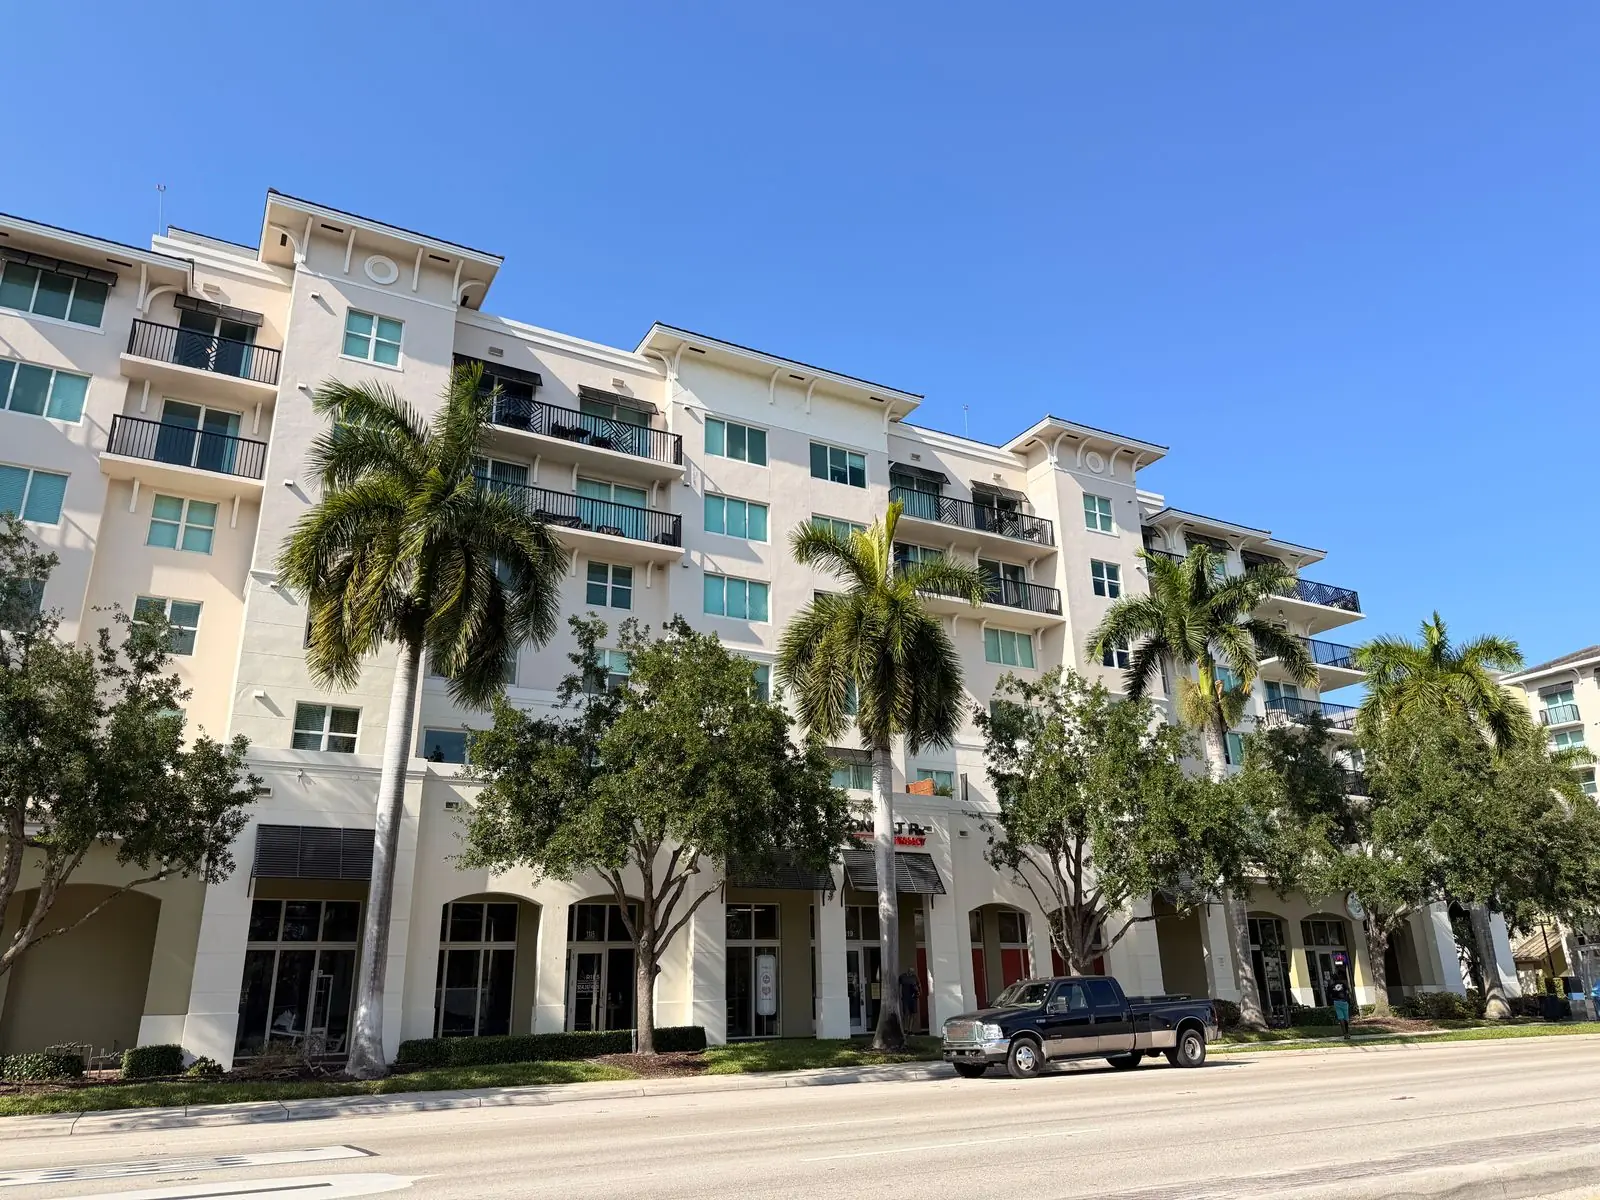
Who insures what in a Florida condo
Florida’s condominium statute and your association’s declaration together divide responsibility. Broadly, the association’s master policy covers the building structure and common elements, while the unit owner’s HO-6 policy covers personal property and certain interior items. Florida law generally excludes items like floor, wall and ceiling coverings, cabinets, countertops and fixtures inside a unit from the association’s insurance obligation, but declarations and older condo documents can vary. Getting this split right is the first step in any condo claim.
Master policy losses for associations
Association claims after a hurricane or major water event can reach across multiple buildings and dozens of roofs, balconies and stairwells. The disputes tend to involve:
- Roof systems across multiple buildings, often with different ages and materials
- Exterior walls, stucco, balconies and railings
- Windows and sliding doors where they are association responsibility
- Elevators, mechanical rooms and common-area finishes
- Code upgrades triggered by the extent of repairs
- Building-wide hurricane deductibles, which for large associations can be substantial
Florida Insurance Appraiser organizes these claims building by building so each component is priced and tracked.
The 2022 condo safety law context
After the Surfside collapse, Florida enacted condo safety legislation in 2022 that introduced milestone structural inspections for certain buildings and structural integrity reserve study requirements. These rules are not insurance coverage provisions, and they do not make an insurer pay for deferred maintenance. They do mean associations are producing more engineering documentation, which can be useful in separating pre-existing conditions from new storm damage during an appraisal.
Unit owner claims under HO-6 policies
Individual owners often find themselves caught between their own carrier and the association’s. A leak from the unit above, for example, may involve the upstairs owner’s policy, your HO-6 and the master policy depending on the source and the materials damaged. We help unit owners value their portion, including interior finishes, contents and loss assessment exposure if the association passes along part of its deductible or a shortfall.
Board approval and authority
For association claims, invoking appraisal is a board decision that should follow the association’s governing documents and Florida’s condominium or HOA statutes. Boards typically want a clear explanation of the dispute, the fee structure and how appraisal interacts with any other professionals on the claim. We are happy to present to a board, and we coordinate with association counsel when one is involved. We are not attorneys and do not give legal advice.
Phasing repairs across a community
Large associations rarely repair every building at once. Contractors may phase work over months, and pricing can shift between phases. An appraisal estimate should reflect a realistic construction schedule, including mobilization for each phase, protection of occupied units and access constraints such as elevator use and parking. We also track which units have interior damage tied to common-element failures, so the association and unit owners each know which portion of the loss falls on which policy.
Coastal and high-rise experience
Much of Florida’s condo inventory sits along the coast, from Miami and Naples to Clearwater and Destin. See our hurricane deductible calculator for a sense of how percentage deductibles scale on large insured values. Florida Insurance Appraiser can assist associations of many sizes, from small villa HOAs to large condominium communities.
What to gather before you call
- Association declaration and insurance responsibility provisions
- Master policy declarations, including hurricane deductible
- HO-6 unit policy, if you are a unit owner
- Milestone inspection or reserve study reports, if available
- Board minutes authorizing the claim or appraisal
- Carrier estimates for each building or unit
Frequently asked questions
Can a unit owner invoke appraisal on the master policy?
Generally the association, as the named insured, controls the master policy claim. Unit owners can typically invoke appraisal on their own HO-6 policies.
Does the 2022 condo safety law change what insurance pays?
Not directly. It added inspection and reserve requirements. Coverage is still governed by the policy, though engineering reports can help document the condition of the building.
Who pays the master policy hurricane deductible?
The association typically bears it, and it may be funded by reserves or assessments. Unit owners may have loss assessment coverage under their HO-6 policies.
Do you work with association attorneys?
Yes. We focus on valuation and coordinate with counsel, who handles legal and coverage questions.